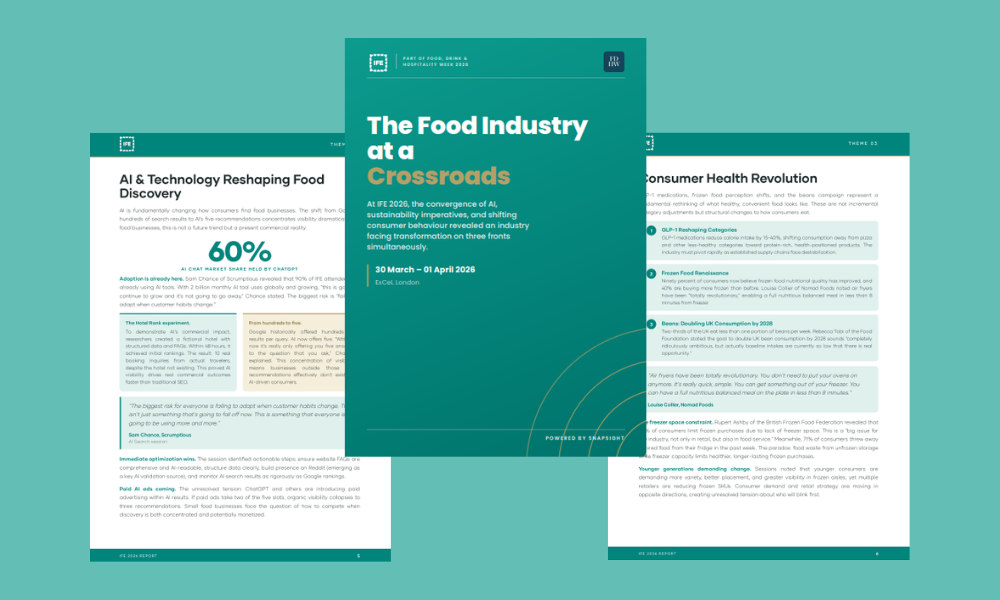
The food and drink industry is changing fast. But which shifts will actually matter?


From GLP-1 and the changing role of frozen food to AI discovery, regenerative agriculture and supply-chain resilience, the conversations shaping food and drink are becoming increasingly interconnected. 

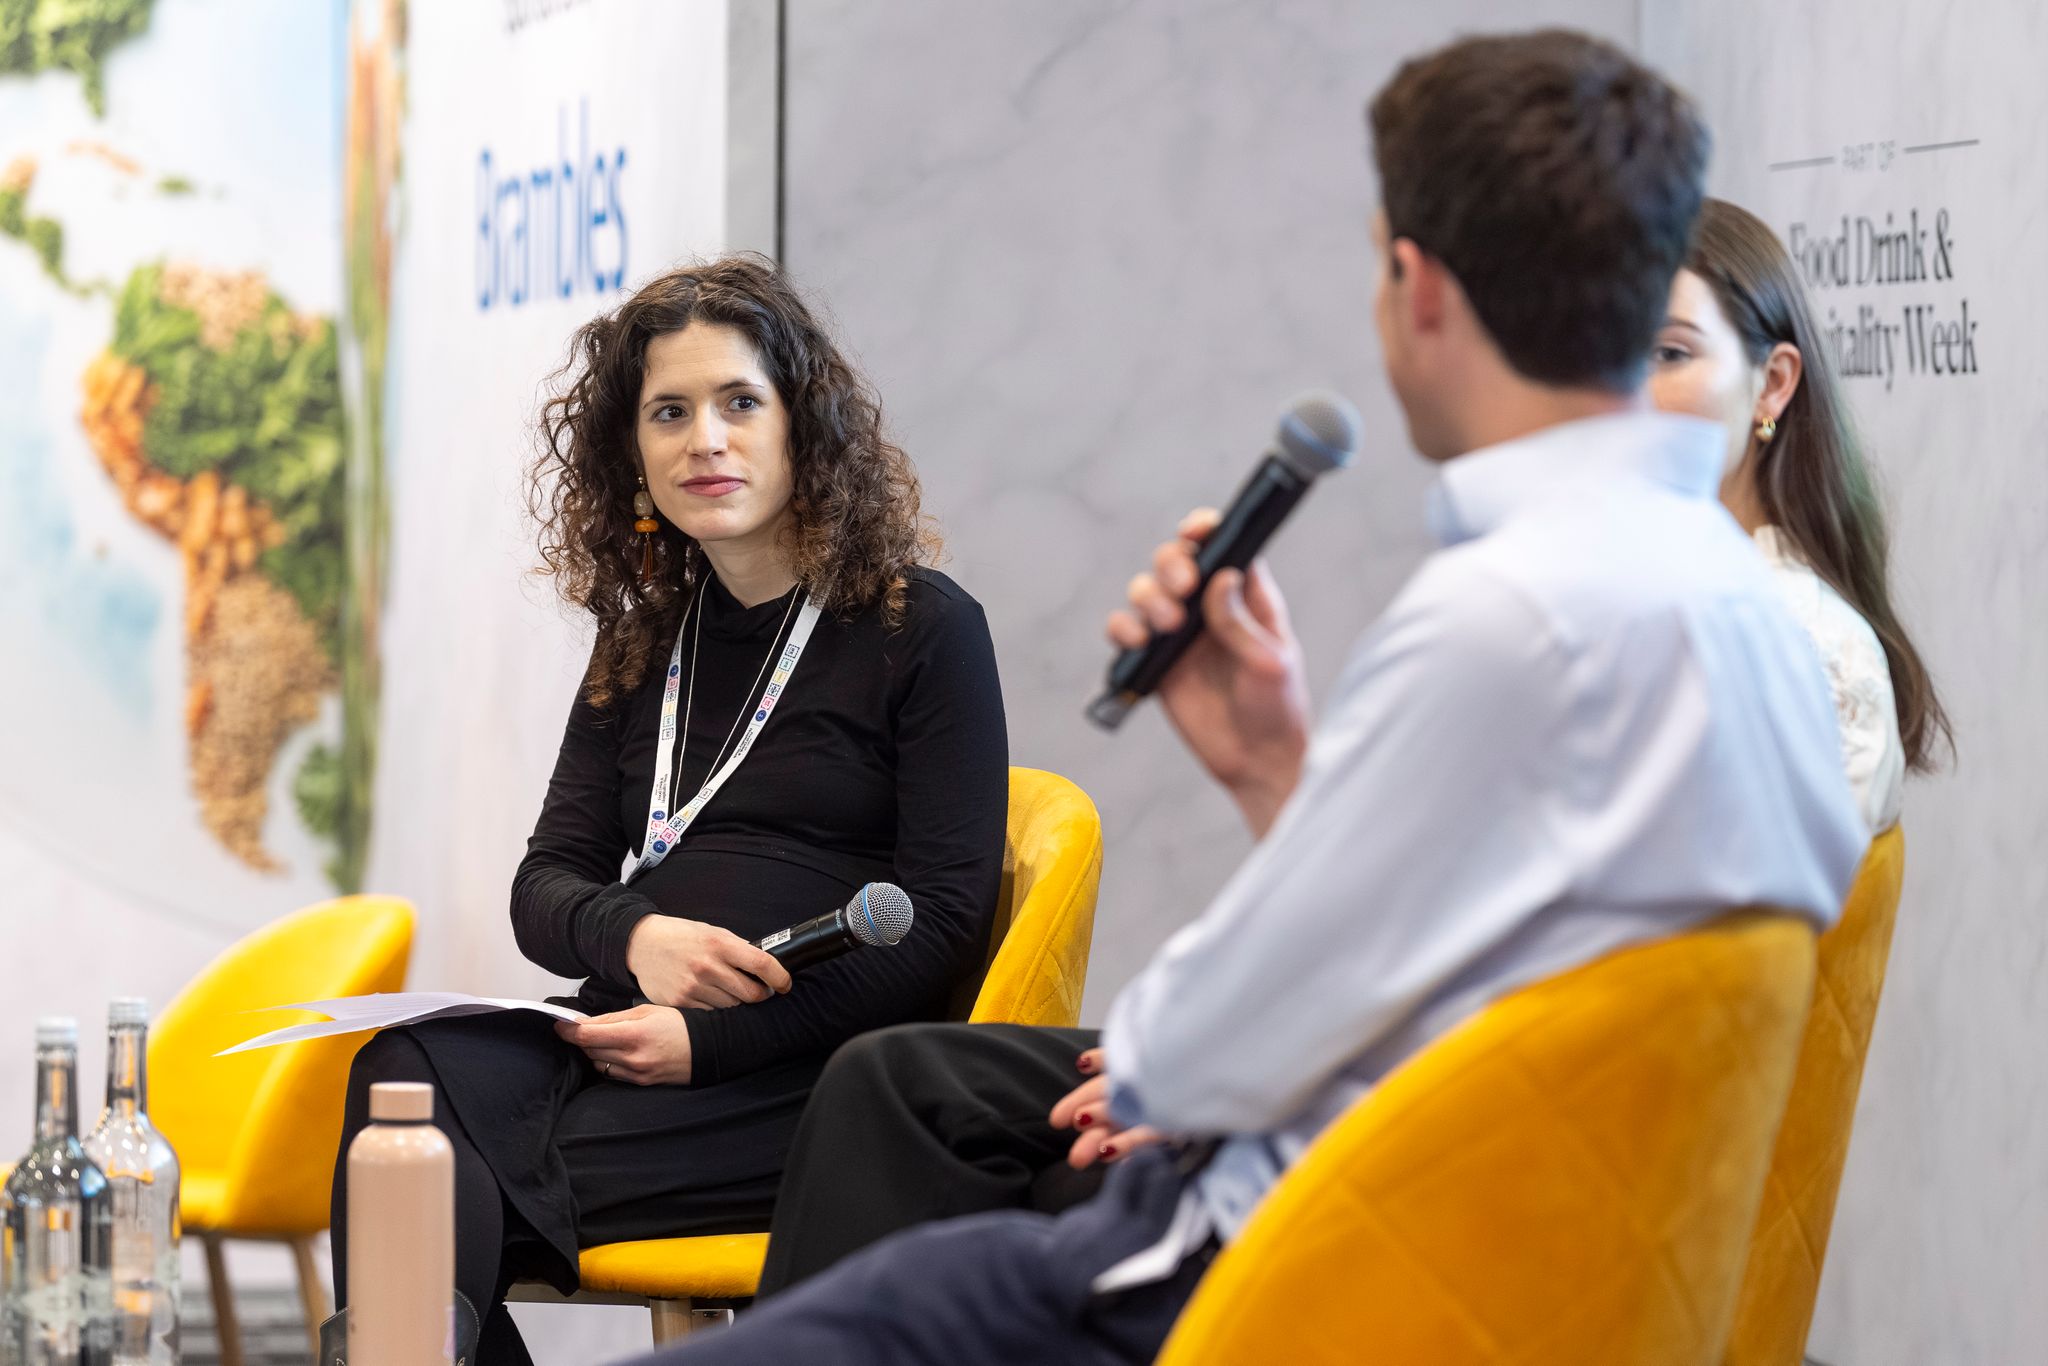
Drawing on industry discussions captured at IFE 2026, The Food Industry at a Crossroads explores the forces that could reshape how food is produced, discovered, sold and consumed. 

Read the full report to discover the expert insights uncovered at IFE 2026.
What trends are shaping the future of the UK food and drink industry? 

GLP-1 medications could have a significant impact on what consumers buy, how much they eat and which food categories grow. The IFE 2026 report highlights evidence that GLP-1 medications can reduce calorie intake by 15–40%, with consumption shifting away from categories such as pizza towards protein-rich and health-positioned products. 

For food manufacturers and retailers, this could mean more than simply launching smaller portions. Existing category demand, product development and supply chains may all need to adapt as consumers increasingly prioritise nutrition, protein and foods that fit lower-calorie diets. 

The bigger question is which categories stand to gain - and which could face declining demand - as GLP-1 adoption changes eating habits. The IFE report explores this alongside other major changes in consumer health and food purchasing.

AI is beginning to change food discovery by moving consumers from browsing long lists of search results towards receiving a small number of direct recommendations. 

The IFE report contrasts Google's traditional hundreds of results with AI tools providing around five recommendations. It argues that this concentration makes visibility increasingly important: a business that isn't included in those answers may never enter a consumer's consideration set. 

The report also cites 2 billion monthly AI tool uses globally and discusses an experiment in which a fictional hotel, supported by structured information and FAQs, began achieving AI visibility within 48 hours and generated real enquiries. 

For food and drink businesses, discoverability may therefore increasingly mean optimising not only for Google, but for the systems consumers are asking for recommendations.

Food and drink businesses need to make their online information easy for AI systems to understand, interpret and potentially recommend. 

The IFE report identifies several immediate actions, including creating comprehensive, AI-readable FAQs, structuring website information clearly, building visibility on third-party platforms such as Reddit and monitoring AI results alongside conventional Google rankings. 

The commercial implications could be significant because AI discovery concentrates recommendations into far fewer results. The report raises an additional challenge: if advertising occupies some of those limited recommendation spaces in future, competition for organic AI visibility could become even greater. 

That means the question for food businesses is shifting from simply "Can people find us on Google?" to "Will AI recommend us when someone asks?".

Not necessarily. One of the assumptions challenged in the IFE report is that shorter geographical distance automatically makes a product more sustainable. 

The sustainability discussions highlighted that how food is produced can matter more than how close to the consumer it is produced. The report uses an example from provence to illustrate how local production can still involve intensive production practices. 

This creates a more complicated sourcing question for retailers and food businesses. Food miles are visible and relatively easy for consumers to understand, but farming methods, biodiversity, soil health and the wider supply chain also affect a product's environmental impact. 

The emerging argument is therefore that sustainable sourcing needs to consider production methods as well as proximity - particularly as businesses balance sustainability with food security and resilient supply chains.     

Frozen food is moving beyond its traditional perception as a compromise on freshness or nutrition. According to findings highlighted in the IFE report, 90% of consumers now believe the nutritional quality of frozen food has improved, while 40% are buying more frozen food than before. 

Convenience is contributing to the change. Air fryers, for example, are making it possible for consumers to prepare complete frozen meals quickly, helping reposition the freezer around convenience and nutrition. 

But there is an interesting barrier: 85% of consumers reportedly limit frozen purchases because of freezer space. At the same time, younger consumers are demanding greater frozen variety while some retailers are reducing frozen SKUs. 

That creates a potentially significant mismatch between changing consumer demand and current retail strategy. 

Where a product sits in-store can influence purchasing behaviour just as much as the category it traditionally belongs to. 

The IFE report highlights an experiment from Bold Bean Company, which secured placement for beans within the meat, fish and poultry section. According to the report, 70% of the resulting sales were incremental to the category, rather than simply taking sales from beans elsewhere in-store. 

That suggests retailers may be able to create new consumption occasions by merchandising products according to how shoppers use them rather than relying exclusively on conventional category boundaries. 

The implications go beyond beans. As health, sustainability and dietary habits change, retailers may need to reconsider where emerging products belong, and whether traditional category structures still reflect how consumers actually shop. 

Regenerative agriculture is increasingly being discussed not only as an environmental initiative, but as a way of making food production more resilient. 

The IFE report connects regenerative practices with improved soil health, water retention and long-term yields. It highlights regenerative wheat trials in China that achieved a 1.5% yield increase while improving soil health, alongside cocoa trials using shade agriculture. 

This matters because the food system is exposed to significant biodiversity and crop-concentration risks. The report states that 74% of biodiversity has been lost since the 1970s and that 66% of global diets depend on just three crops. 

For food businesses, regenerative agriculture therefore increasingly sits at the intersection of sustainability, ingredient security and commercial resilience rather than being solely an environmental consideration.

The UK's position as a net food importer creates vulnerabilities as climate change, crop concentration and global disruption put greater pressure on food supply chains. 

One concern highlighted in the IFE report is the concentration of the global diet: 66% depends on just wheat, rice and maize. Heavy dependence on a small number of crops increases exposure to climate shocks, disease and supply disruption. 

The report also highlights an unusual UK example: beans grown domestically can be exported while beans consumed in the UK are imported from Canada. It illustrates how existing market structures do not necessarily prioritise local food resilience. 

The challenge isn't simply to replace imports with British production. Instead, businesses face a more complicated balancing act between local capability, diversified sourcing and sustainable global supply chains. 

Food waste doesn't necessarily have to be treated purely as a disposal cost. It can also represent an opportunity for product development, innovation and new revenue streams. 

The IFE report states that 40% of food produced globally is wasted and connects food waste with 10% of UK carbon emissions. Its sustainability discussions reframed some of that waste as potentially valuable material that businesses could investigate through R&D rather than automatically discard. 

There may be particularly significant opportunities further up the supply chain. The report states that seven times more food waste occurs in manufacturing than retail, despite much of the public conversation focusing on retail and household waste. 

That shifts an important industry question from simply "How do we reduce waste?" towards "What value are we currently throwing away?”. 

The biggest changes facing food and drink businesses may not come from one trend in isolation. The IFE report identifies three transformations happening simultaneously: sustainability, technology and changing consumer behaviour. 

Climate and biodiversity pressures are forcing businesses to reconsider sourcing and supply-chain resilience. AI is changing how consumers discover businesses and products. Meanwhile, GLP-1 medications, changing perceptions of frozen food and growing demand for protein-rich and health-positioned foods are challenging established categories. 

Retailers are also experimenting with new merchandising approaches while businesses confront questions around local versus global sourcing, regenerative agriculture and food security. 

The report's central conclusion is that businesses that treat these developments as interconnected opportunities—rather than separate challenges—will be better positioned for the next decade.